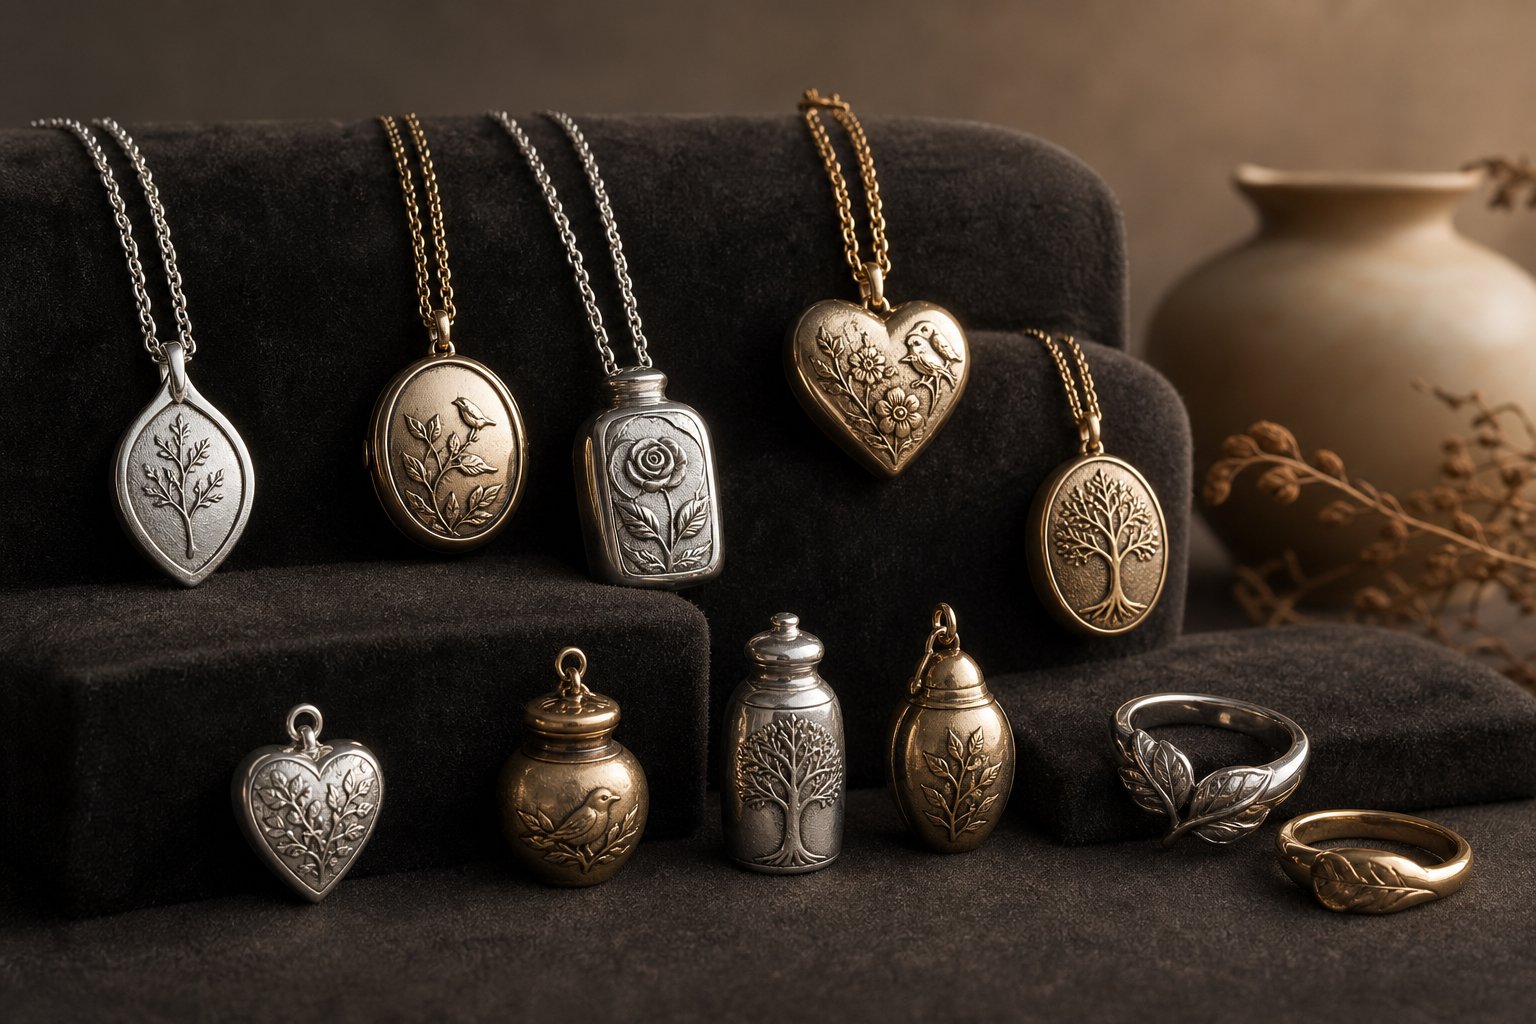
Ask who buys pet memorials and you will hear "everyone who loved their pet." True, and useless for planning. Assortment, channel and tone decisions all depend on which cohort completes the purchase — and the honest answer is that the data is directional, not definitive. This piece lines up what the sourcing actually shows about Gen Z, millennials and the generations around them, labels the soft numbers for what they are, and converts the signal into product decisions.
What the sourcing shows, with quality labels
- Ownership is broadening downward in age. APPA's State of the Industry reporting credits Gen Z, millennial and Gen X owners jointly for recent growth, with Gen X dog ownership up 12% and cat ownership up 8% year over year (APPA, 2025-2026 releases).
- Gen Z households surged. Gen Z pet-owning households grew from roughly 13.1 million in 2023 to 18.8 million in 2024, about +43.5% (PetfoodIndustry reporting APPA data — secondhand, medium confidence).
- The youngest appear to spend most. A Harris Poll reported via The Independent puts annual pet spending at about 6,103 USD for Gen Z owners, 5,150 USD for millennials and 2,454 USD for boomers (secondhand, lower confidence — use as a soft signal only).
- The attitude base holds. 97% of US pet owners call their pet a family member, and 51% call it equal to a human one (Pew Research Center, 2023) — the shared belief that underwrites every cohort's memorial purchase.
- Marketplace visibility is real. Etsy's own market pages aggregate "pet memorial" gifts, and the search term ranked inside Etsy's top searches in Q3 2025 per the eRank tool (tool-derived figures — indicative, not audited).
Cohorts at a glance
| Cohort | What the sourcing shows | Selling implication (inference) |
|---|---|---|
| Gen Z | Fastest-growing owner households (+43.5% in one year, APPA data via PetfoodIndustry); highest annual spend per the Harris Poll figures | Jewelry-first and personalization-first; discovered through social; reads grief copy for authenticity and distrusts sales pressure |
| Millennials | Core owning cohort; mid-5,000 USD annual spend per Harris Poll (secondhand) | Keepsake splits for young families; bundles that serve "our pet" remembrance; expects quality materials documented |
| Gen X | Dog ownership +12%, cat +8% year over year (APPA) | Wood and stone lines with substance; buys through vet and established retail channels |
| Boomers | Lowest annual spend per Harris Poll (secondhand); long-established owners | Classic urn and memorial stone forms; values phone-and-email service and clear sizing guidance |
One more observation from the marketplace side: handmade-style, personalized memorial pieces dominate Etsy's pet memorial pages, and keepsake jewelry is the most crowded white-label lane on the wholesale platforms we track. Younger buyers are not buying less — they are buying differently: smaller, more personal items, often as gifts for someone who lost a pet (inference).
Merchandising for the young grief customer
- Lead with jewelry and small keepsakes. Low ticket, high meaning, light shipping — our keepsake jewelry line starts at MOQ 50 pcs with name engraving.
- Make personalization instant. Photo-based items (UV printing on frames and figurines) and name-date engraving convert best when the mockup is visible before checkout.
- Write for the person buying as a gift. A large share of memorial purchases are for a friend who lost a pet; copy should speak to the giver, not only the owner.
FAQ
Which generation buys the most pet memorials?
No sourced statistic answers that directly. The signals point to younger cohorts driving category growth: Gen Z owner households grew about 43.5% in a single year (APPA data via PetfoodIndustry), and millennials remain a core owning cohort. Treat cohort share as a planning hypothesis to validate with your own sales data.
Do younger owners really spend more on their pets?
Harris Poll figures reported via The Independent put Gen Z owners at about 6,103 USD per year versus 2,454 USD for boomers — but these are secondhand and should be used as soft signals. The harder fact is APPA's attribution of industry growth to Gen Z, millennial and Gen X owners.
What products skew younger?
Keepsake jewelry, photo-personalized frames and small personalized items — consistent with the handmade, personal style dominating Etsy's pet memorial pages and with young buyers' gift-giving behavior (inference, supported by marketplace signals).
How do I market to Gen Z without being tone-deaf?
Write honestly about grief, show real personalization before purchase, avoid urgency tactics entirely, and let the product carry the emotion. Respect reads as competence with this cohort.
Sources and notes: APPA State of the Industry releases (2025-2026) for cohort growth attribution and Gen X ownership shifts; PetfoodIndustry (2024) for Gen Z household growth citing APPA — secondhand; Harris Poll via The Independent for per-cohort annual spending — secondhand, lower confidence; Pew Research Center (2023) for the 97%/51% attitudinal base; Etsy market pages and eRank Q3 2025 search data as tool-derived marketplace signals. Cohort-level selling implications are PAWSANGEL inferences, as labeled.
Sourcing for a younger customer base?
Start with keepsake jewelry and photo-personalized pieces — MOQ from 50 pcs, engraving and UV printing from the first sample. Reply within 12 business hours.